中国生物科技2026:美国内部博弈观察(中篇)
中国生物科技2026:美国对抗美国(中篇)
摘要
本文为中国生物科技行业观察评论,由许先锋(PhD, JD)口述并经AI转录翻译,聚焦2026年中美生物科技领域博弈态势,分析美国内部政策分歧对中国生物科技企业的影响。属于个人观点,不代表任何机构立场。
AI 主编 · 推荐理由推荐理由
中美博弈持续升级,美国内部矛盾或为中国生物科技企业创造窗口期,建议BD和注册团队动态跟踪政策分野,调整出海与管线策略。
五维评分
正文

去年,我曾把中国(China)生物科技领域的一个决定性趋势概括为“中国制造,全球变现”(“Made in China, Monetized Globally”)。中国企业在国内高效开发药物资产,并将其授权给全球制药公司。
一年之后呢?交易流量加速了。源自中国的授权交易不再是全球制药业务拓展(pharma BD)中的边角戏,而已成为主戏的一部分。
一个容易给出的解释,是中国以中央规划为基础的产业政策。这当然没错,但并不完整。北京(Beijing)确定战略行业,省级和市级政府则提供资本、设施、激励措施和人才计划。然而,中国并不是简单地选出一家抗体偶联药物(ADC)公司或细胞疗法公司作为国家级冠军。数百家公司在竞争。上海(Shanghai)与苏州(Suzhou)竞争;北京(Beijing)与深圳(Shenzhen)竞争;地方政府争夺企业;企业争夺资本、科学家和合作伙伴。
中国把自上而下的产业优先布局,与自下而上的达尔文式(Darwinian)竞争结合起来。
这种竞争非常激烈。在中国度过三周期间,有一件事不可能不注意到:人们工作得异常努力。跨境BD电话往往深夜才进行。周末也有人回复消息。公司以惊人的速度作出决定。我自认为是一名相当勤奋的美国律师,但我不确定自己是否愿意和普通的中国生物科技创始人比拼工作时长。
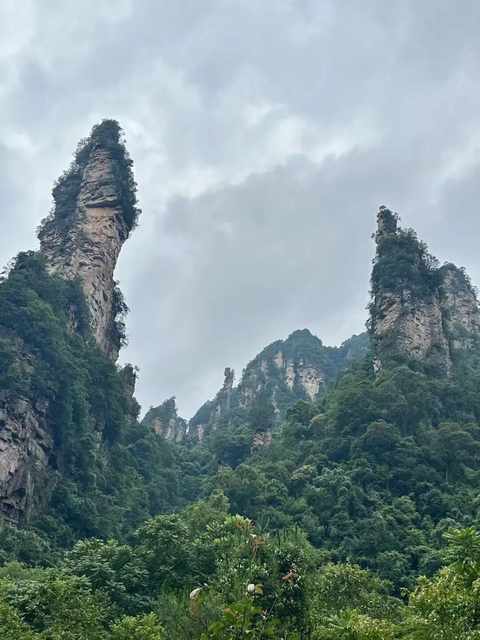
速度与互联互通是中国生物科技崛起的基石,并渗透到日常生活的方方面面。这是一种这样的文化:高铁乘务人员在几秒钟内完成列车清理,以便列车返程,而全天候(24/7)联网则是默认状态。我曾在偏远的国家公园收到微信(WeChat)消息;在美国(America),那种地方我本来会完全没有信号。在这样的环境中,“永远在线”不是一项政策,而是每个人呼吸的空气。
确实,每个人都在以每小时120英里的速度驾驶——有些人是因为喜欢开快车,另一些人则是因为身后的车正以每小时121英里的速度追来。这带来了巨大的执行速度。但它也提出了我去年问过的一个问题:如果每个人都在以每小时120英里的速度驾驶,谁还有时间看看窗外?
真正的0→1创新需要智慧和努力,但有时也需要失败、漫无目的的探索、奇怪的想法、无聊,以及偶然发现。一个为下一个IND、下一轮融资或下一笔许可交易而优化的超级竞争型生态系统,是否能为那些回报无法在明年的PowerPoint演示文稿中呈现的想法留出足够空间?我仍然不知道。
TONACEA
需要一个完整的生态系统
CPIC上的一个场景一直留在我的脑海中:供应商无处不在——CRDMO、CDMO、CRO、检测公司、临床服务提供商以及专业技术平台。中国已经围绕药物开发企业建立起庞大的产业基础设施。这一生态系统是企业得以快速行动、并不断提高成本效率的一个常被低估的原因。
因此,速度并不只是单个公司的特征。速度也可以成为一种生态系统特征。当有经验的供应商环绕一家初创企业时,初创企业无需事事从头搭建。供应商之间展开激烈竞争。科学家在不同公司之间流动。专业诀窍不断扩散。经验持续积累并产生复利效应。
这看起来就不再只是“廉价的中国研发”,而更像是中国在其他行业形成的集群优势。一家位于上海的领先ADC生物科技公司的创始人告诉我,他可以在方圆一百英里内找到他的公司所需的一切。这引出了一个让美国推动产业回流颇为尴尬的问题:你能复制这种优势吗?你可以补贴一家工厂,但你能补贴一个生态系统吗?
CPIC还揭示出,创新供给可能暂时过剩。寻求全球资本和合作伙伴的中国卖方数量,远远超过了国际买方的数量。这会损害单个中国公司的估值和议价能力,但拥有过多潜在有吸引力的治疗性资产,算得上一个相当令人羡慕的产业难题。对全球制药公司而言,这造就了买方市场。我在条款清单本身就能看到这种不对称性;不过,我坐在谈判桌哪一边,这种不对称性呈现出的样子也不一样。
TONACEA
政府资本
去年,我曾开玩笑地把中国的体系称为“具有中国特色的风险资本主义”(“Venture Capitalism with Chinese Characteristics”),简称VCCC。一年之后,我或许可以把它进一步简化为:VC越来越代表政府资本(goVernment Capital)。
其中存在一些显而易见的问题。政府资本可能错配资源、鼓励重复建设,并让实力较弱的公司继续存活。但完全否定政府资本,也会忽略一个事实。生物技术极其资本密集,研发周期漫长,而且会产生私人投资者可能无法完全获得的价值。私人资本追求回报最大化;政府有时则追求产业能力最大化。
那么,当政府支持的资本与传统风险投资展开竞争时,会发生什么?哪一种资本能更长时间地承受亏损?哪一种能更好地配置资源?哪一种能创造突破性科学,哪一种又能建设产业能力?答案可能会因时间跨度不同而不同。
美国还保有另一项难以量化的优势:对失败的容忍度。在波士顿(Boston)或硅谷(Silicon Valley),一家失败的初创企业可以成为创业者履历的一部分:你尝试过、失败过、学到了东西,然后再次尝试。伤疤可以变成勋章。中国的创业文化传统上宽容度较低。这一点很重要,因为激进式创新需要人们愿意让自己看起来很愚蠢,并且偶尔一败涂地。
TONACEA
0 → 1 → 10 → 100
下面是越来越多人采用的一种思维模型。美国历来擅长0→1:基础发现、新生物学、新靶点和新模态。中国正在变得极其擅长1→10:工程化、优化、临床前工作、制造和早期临床开发。美国在10→100方面仍占据主导:全球开发、商业化、资本市场和价值获取,而美国(U.S.)制药市场的经济实力为此提供了巨大助力。
现实显然更加复杂,但这个模型提出了一个重要问题:如果美国越来越失去1→10,它还能永远守住0→1吗?
创新生态系统存在反馈回路。研究生需要职业发展。药物化学家需要项目。工艺开发专家需要设施。经验丰富的产业科学家会成为创始人、投资者和导师。你不可能无限期地掏空一个生态系统的中部,却假设起点仍能不受影响。
人才也是如此。美国最终的优势从来不只是金钱;而是它吸引来自世界各地、胸怀抱负的人才的能力。
我现在认识的许多中国生物科技领袖都曾在美国接受教育或培训,对美国的科学、商业文化和资本市场有着非同寻常的理解。反过来问:有多少美国生物科技高管能够以同等深度理解中国?——这种不对称十分醒目。
人才用脚投票。如今,人才有更多地方可以投票。
先发者还面临一个日益严重的问题。专利申请会公开,科学数据即时传播,全球CRO基础设施使实验更易于复现,而人工智能(AI)使已发表的信息更容易被发现和整合。尤其是在生物大分子领域,竞争者不必复制先行者分子;他们可以围绕已经验证的靶点设计不同的分子。
率先行动的经济价值,是否仍然足以抵偿率先行动的成本?专利制度以披露换取排他性,但披露可能早在药物上市前许多年就已经发生。以我的经验,在分子进入临床前许多年就确定的专利申请策略和权利要求保护范围的先后布局,往往会悄然决定规避设计的难易程度。经过周密规划的公开时机和生命周期规划,其影响可能不亚于最初的专利申请。对先行者保护过度,就会压制竞争;保护不足,最终愿意成为先行者的人会越来越少。
这就把我们带到了效率与韧性的碰撞。如果中国能够以更快的速度、更少的资本开发出有前景的临床资产,美国制药公司为什么不应当将其授权引进?患者希望获得好药;公司希望拥有产品管线;投资者希望获得回报。癌症没有护照。
然而,政府会优化资本市场不会优化的事项:就业、供应链、国内能力、国家安全以及未来的产业能力。
单笔交易的最低成本,并不一定等于国家战略的最低成本。
这正是我的中国之行与华盛顿特区(Washington D.C.)——我的大本营——直接碰撞之处。
下一篇:大棒来了。
(上下滑动查看更多)
China Biotech 2026: America Against America
Authored by Morgan Xu, PhD, JD (LinkedIn) dictated, ChatGPT transcribed;
Part II — Everyone Is Driving 120 MPH
Last year I described one of the defining trends in China biotech as “Made in China, Monetized Globally.” Chinese companies were developing assets efficiently at home and licensing them to global pharmaceutical companies.
One year later? The deal flow intensified even more. China-origin licensing is no longer a sideshow to global pharma BD. It is part of the main show.
An easy explanation is China’s central planning-based industrial policy. That’s true, but awfully incomplete. Beijing identifies strategic sectors, and provincial and municipal governments provide capital, facilities, incentives and talent programs. Yet China does not simply select one ADC company or cell-therapy company as a national champion. Hundreds compete. Shanghai competes with Suzhou; Beijing with Shenzhen; local governments compete for companies; companies compete for capital, scientists and partners.
China combines top-down industrial prioritization with bottom-up Darwinian competition.
That competition is intense. During three weeks in China, one thing was impossible to miss: people work incredibly hard. Cross-border BD calls happen late at night. Messages get answered over weekends.
Companies make decisions at astonishing speed. I consider myself a reasonably hardworking American lawyer, but I am not sure I want to enter a work-hours competition with the average Chinese biotech founder.
Speed and connectivity are the bedrock of China’s biotech ascent, and they permeate every facet of everyday life. It’s a culture where high-speed rail crews clear trains in seconds for the return leg and 24/7 connectivity is the default. I’ve fielded WeChat messages from remote national parks where I would have zero signal in America. In this environment, "always on" isn't a policy—it’s the air everyone breathes.
Indeed, everyone is driving 120 MPH—some because they love driving, others because the car behind them is going 121. That creates enormous execution speed. But it also raises a question I asked last year: if everybody is driving 120 MPH, who has time to look out the window?
True 0-to-1 innovation requires intelligence and hard work, but sometimes also failure, wandering, strange ideas, boredom and serendipity. Can a hypercompetitive ecosystem optimized for the next IND, financing round or licensing deal leave enough room for ideas whose payoff cannot fit into next year’s PowerPoint? I still don’t know.
It takes an ecosystem
One image from CPIC stayed with me: vendors everywhere—CRDMOs, CDMOs, CROs, testing companies, clinical-service providers and specialized technology platforms. China has built an enormous industrial infrastructure around drug developers. That ecosystem is an underappreciated reason companies can move quickly and increasingly cost-efficiently.
Speed is therefore not merely a characteristic of an individual company. Speed can become an ecosystem characteristic. A startup does not need to build everything when experienced suppliers surround it. Vendors compete aggressively. Scientists move between companies. Know-how diffuses. Experience compounds.
That begins to look less like “cheap Chinese R&D” and more like the cluster advantage China developed in other industries. A leading Shanghai ADC biotech founder told me that he could find anything his company needs within a hundred miles. Which raises an awkward question for American reshoring: can you match that advantage? You can subsidize a factory, but can you subsidize an ecosystem?
CPIC also revealed what may temporarily be an oversupply of innovation. The number of Chinese sellers seeking global capital and partners far exceeded the number of international buyers. That hurts valuations and bargaining power for individual Chinese companies, but having too many potentially interesting therapeutic assets is a rather enviable industrial problem. For global pharma, it creates a buyer’s market. I can witness that asymmetry in the term sheets themselves, although it looks different depending on which side of the table I am sitting on.
goVernment Capital
Last year I jokingly called China’s system “Venture Capitalism with Chinese Characteristics”—VCCC. One year later, I might simplify it: VC increasingly stands for goVernment Capital.
There are obvious problems. Government capital can misallocate resources, encourage duplication and keep weak companies alive. But dismissing it altogether also misses something. Biotechnology is exceptionally capital-intensive, has long development cycles and generates benefits that private investors may not fully capture. Private capital optimizes returns; governments sometimes optimize industrial capacity.
So what happens when government-backed capital competes with conventional venture capital? Which tolerates losses longer? Which allocates resources better? Which creates breakthrough science, and which builds industrial capacity? The answer is probably different over different time horizons.
America retains another difficult-to-measure advantage: its tolerance for failure. In Boston or Silicon Valley, a failed startup can become part of an entrepreneur’s résumé: you tried, failed, learned, and try again. The scar can become a medal. Chinese entrepreneurial culture has traditionally been less forgiving. That matters because radical innovation requires people willing to look stupid and occasionally fail spectacularly.
0 → 1 → 10 → 100
Here is the mental model many increasingly adopt. America historically excels at 0→1: fundamental discovery, new biology, new targets and modalities. China is becoming extraordinarily good at 1→10: engineering, optimization, preclinical work, manufacturing and early clinical development. America remains dominant at 10→100: global development, commercialization, capital markets and value capture, helped enormously by the economic power of the U.S. pharmaceutical market.
Reality is obviously more complicated, but the model raises an important question: if America increasingly loses 1→10, can it keep 0→1 forever?
Innovation ecosystems have feedback loops. Graduate students need careers. Medicinal chemists need projects. Process-development experts need facilities. Experienced industrial scientists become founders, investors and mentors. You cannot hollow out the middle of an ecosystem indefinitely and assume the beginning remains unaffected.
The same is true of talent. America’s ultimate advantage has never simply been money; it has been its ability to attract ambitious people from everywhere.
Many Chinese biotech leaders I know or meet were educated or trained in America and understand American science, business culture and capital markets remarkably well. Ask the reverse question—how many American biotech executives understand China with comparable depth?—and the asymmetry is striking.
Talent votes by feet. Today talent has more places to vote for.
There is also a growing first-mover problem. Patent applications publish, scientific data travel instantly, global CRO infrastructure makes experiments easier to reproduce, and AI makes published information dramatically easier to find and synthesize. Particularly in biologics, competitors need not copy the pioneer molecule; they can design different molecules around a validated target.
Is being first still economically valuable enough to pay for being first? The patent system trades disclosure for exclusivity, yet the disclosure can arrive many years before a drug reaches market. Protect pioneers too much and you suppress competition. Protect them too little and eventually fewer people want to pioneer. In my experience, filing and claim-scope sequencing decisions made years before a molecule reaches the clinic quietly determine how easy a design-around will be.
Meticulously planned publication timing and lifecycle planning can be as consequential as the initial patent filing.
That brings us to the collision between efficiency and resilience. If China can produce a promising clinical asset faster and with less capital, why shouldn’t American pharma license it? Patients want good drugs; companies want pipelines; investors want returns. Cancer does not carry a passport.
Governments, however, optimize for things capital markets do not: employment, supply chains, domestic capabilities, national security and future industrial capacity.
The cheapest individual transaction is not necessarily the cheapest national strategy.
That is where my China trip runs directly into Washington D.C., my home base.
Next: Here come the clubs.
相关阅读